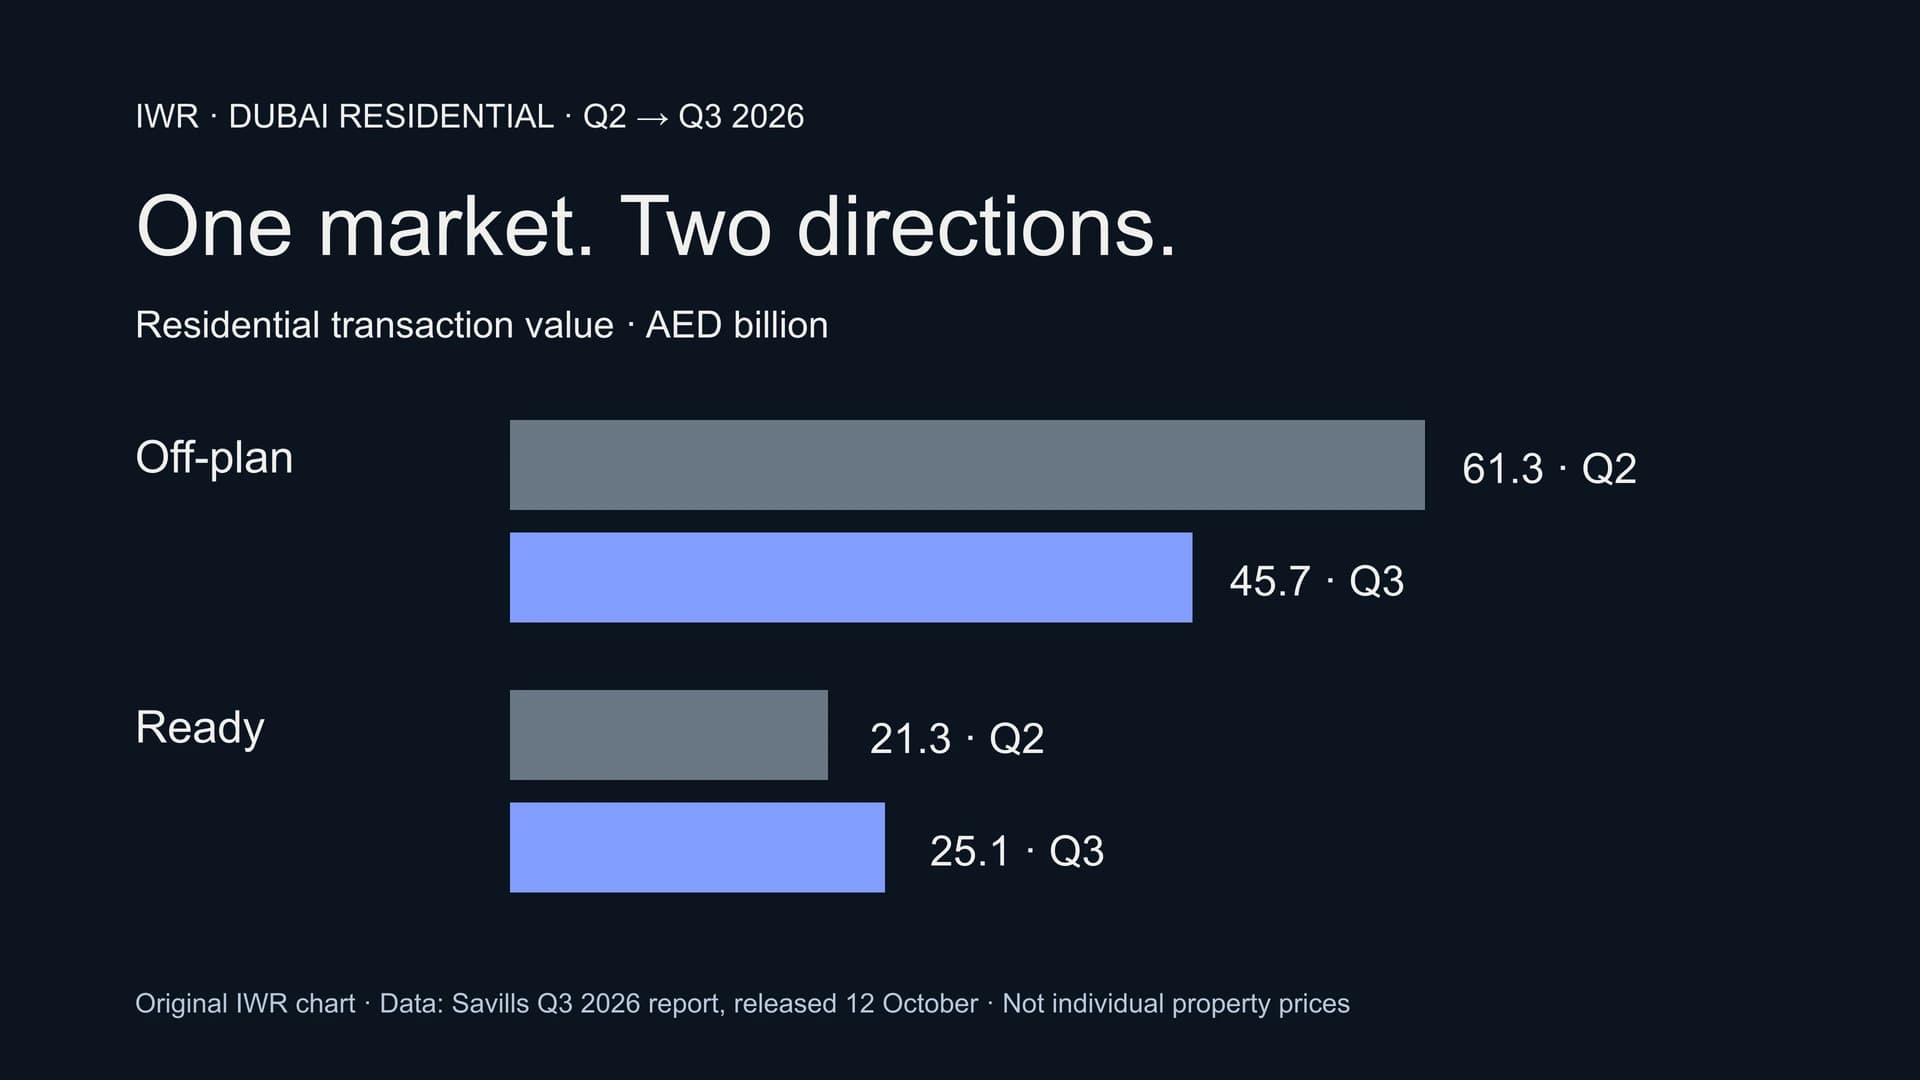
Savills published its Dubai residential Q3 report on 12 October. It records AED70.8 billion of residential transactions, against AED82.6 billion in Q2. But completed-home sales value increased from AED21.3 billion to AED25.1 billion, while off-plan value fell from AED61.3 billion to AED45.7 billion. The decline in the combined total therefore conceals different movements within the market.
The report also distinguishes changes in the mix of traded homes from matched-property pricing. Savills reports a 4.8% quarterly fall in average apartment prices, compared with a smaller 1.7% decline in its matched-property comparison. Its interpretation is that changing stock contributes to the headline movement; that is not proof that every apartment has become cheaper.
The aggregate does not price your shortlist
For an acquisition shortlist, this distinction changes the first question. Instead of taking a citywide percentage off an asking price, establish which comparable homes actually traded. Match location, building, size, condition and delivery stage. A different sample of purchases can change an average without changing the value of a particular home by the same amount.
Transaction value needs a separate reading again. It combines the number of deals with the amounts paid. Higher completed-home sales value alone cannot establish whether a particular building’s prices rose, whether more units traded, or whether buyers selected larger homes. The aggregate is a useful signal about activity, not a unit valuation.
An off-plan purchase and a completed home also expose the buyer to different practical commitments. One comparison needs the construction timetable, instalments and delivered specification. The other can include inspection of the actual rooms and surrounding facilities. Put both on a consistent capital-to-occupation basis, rather than comparing only deposits or advertised price per square foot.
Compare the same commitment
For an owner planning to let a home, the same discipline applies to income. Price the likely tenant’s alternatives in the specific building and neighbourhood. A broader increase in activity does not establish an achievable rent, eliminate vacancy or settle the annual ownership budget.
The useful next evidence is a dated set of comparable transactions and available alternatives for the exact shortlist. Savills’ new report helps identify why one headline is insufficient; the purchase decision still belongs at property level.