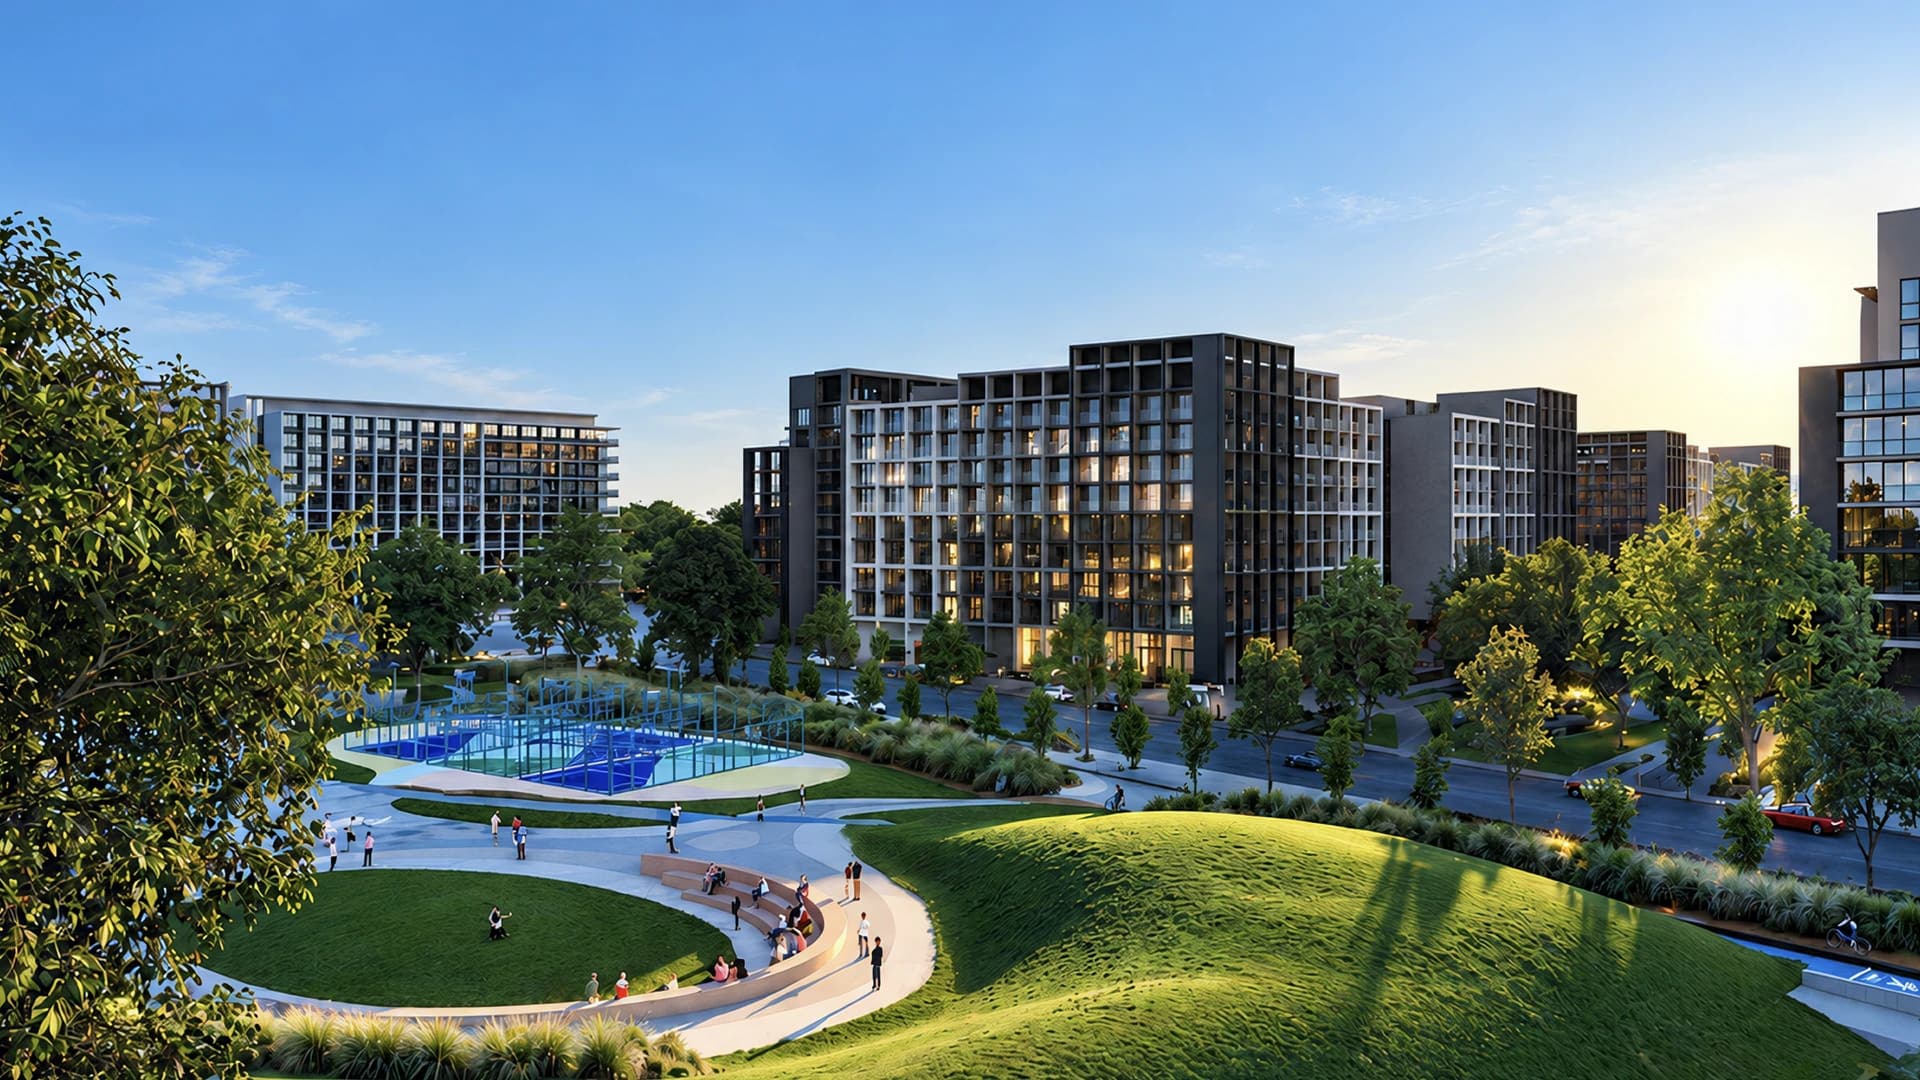
Aldar has agreed to buy nine residential buildings from Arada in Sharjah’s Aljada community for AED1.1 billion. Announced on 15 October, the forward purchase covers more than 1,100 homes across three blocks, with delivery scheduled for the fourth quarter of 2029. It is Aldar’s first real estate investment in Sharjah.
The acquisition is intended to expand Aldar’s residential-for-rent portfolio. Its announcement puts the wider develop-to-hold pipeline across sectors at AED21 billion. That is a programme of future assets, not a statement that the new Aljada homes are already generating rent.
A different transaction from the Abu Dhabi partnership
The two companies announced approximately AED15 billion of development opportunities on 30 September. Those arrangements concern a joint venture at Seih Sdeirah and Arada’s acquisition of three residential plots on Yas Island. The new deal reverses the geographic direction: Aldar is acquiring future buildings in Arada’s established Sharjah community.
The values describe different things. A development-opportunity figure is not the same as the price of a forward-purchase package. Adding them together as completed property sales would obscure the transactions rather than measure a new market total.
For an individual investor, the ownership model also matters. A company assembling a rental portfolio can assess buildings together, their operating arrangements and their relationship with the rest of its holdings. A person buying one apartment has a different concentration of costs, tenants and exit options. The institutional purchase is evidence of Aldar’s capital commitment; it is not a substitute for underwriting a particular home.
Why the package price is not a retail valuation
The announcement gives an aggregate value and a count above 1,100 units, not a schedule of apartment sizes, types and individual prices. It does not disclose the payment timetable or expected rental income. Dividing the headline amount by a rounded unit count would produce an apparent average without identifying what that average includes.
A useful retail comparison would instead match an actual home with alternatives of similar floor area, layout, condition and delivery status. An apartment’s charges, furnishing needs and expected letting costs belong beside its price. Without an agreed rent and the relevant costs, the announcement cannot establish a net yield for the acquired buildings or a neighbouring unit.
Aljada is not an entirely undelivered setting. The companies report more than 8,800 homes handed over since 2021. That provides a separate existing neighbourhood to examine, but does not turn the nine newly contracted buildings into completed stock. A visit to an operating part of the community and a review of the future building’s specification answer different questions.
Follow the path from acquisition to occupation
For this investment, Q4 2029 is the announced delivery target. Completion, occupation and stabilised letting are distinct milestones; a forward-purchase announcement establishes none of the latter two. Nor does a residential-for-rent strategy demonstrate that every eventual tenant will accept a particular rent.
The next useful disclosures are the buildings’ delivery progress, detailed accommodation mix, operating arrangements and, when available, achieved leases. Those would show how the future portfolio is becoming usable rental housing. For buyers comparing their own options today, the immediate lesson is narrower: Aldar has chosen to enter Sharjah through a sizeable future rental portfolio, while the price and income case for each individual home still needs its own evidence.